Global markets experienced another volatile week as investors weighed renewed concerns over artificial intelligence (AI) investment, rising energy prices and the outlook for interest rates. Technology shares came under pressure, while defensive sectors and government bonds benefited from a shift in investor sentiment. Meanwhile, escalating tensions in the Middle East pushed oil prices higher, adding to inflation concerns ahead of several important central bank meetings.
In the US, technology shares led the declines as investors increasingly questioned the scale and sustainability of AI-related investment. Semiconductor stocks were particularly hard hit, with the Philadelphia Semiconductor Index falling approximately 4% over the week. Concerns around elevated capital expenditure, rising debt levels and whether future earnings can justify current valuations weighed on sentiment. However, the weakness did not extend across the broader market, with investors rotating towards more defensive sectors, including utilities, consumer staples and healthcare.
US economic data continued to reflect a resilient economy, although signs of pressure are emerging. October’s preliminary Composite PMI eased to 57.6 from 58.4, still indicating robust business activity, but businesses reported their sharpest increase in selling prices since August 2022. Meanwhile, the housing market remained under pressure, with pending home sales falling 7.3% in September to a record low. Initial jobless claims declined to 194,000, suggesting labour market conditions remain relatively stable.
Bond markets benefited from the cautious sentiment, with the US 10-year Treasury yield retreating to around 5.0% from a recent peak of 5.3%. Attention now turns to the Federal Reserve’s meeting on 27–28 October, where policymakers are widely expected to leave interest rates unchanged following September’s increase. However, persistent inflation pressures, particularly from energy prices, could complicate the outlook for further policy tightening.
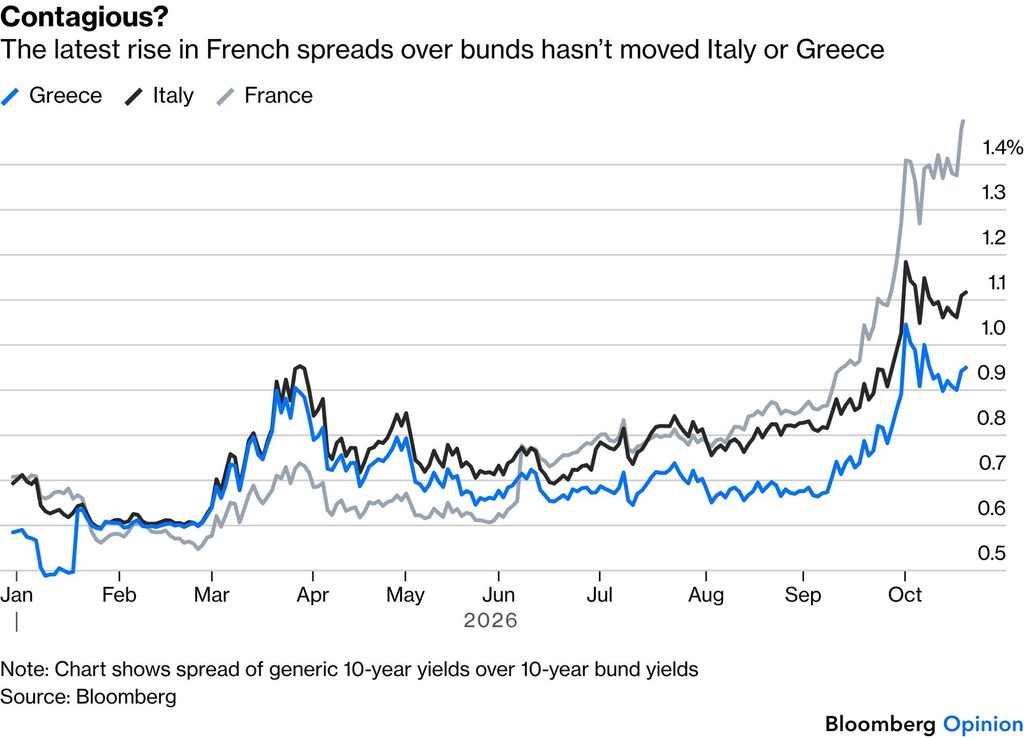
In Europe, France’s deepening political and fiscal challenges dominated headlines. Widespread protests and civil unrest added to concerns over the country’s deteriorating finances, pushing government borrowing costs sharply higher. However, Moody’s unexpectedly maintained France’s Aa3 credit rating on Friday, providing some relief, although its negative outlook highlights the challenges that remain. Elsewhere, eurozone business activity slowed, with the October Composite PMI declining to 51.9 from 53.1, reinforcing concerns about the strength of the region’s economic recovery.
In the UK, inflation rose to 3.5% year on year in September, ahead of expectations, driven largely by higher fuel prices. While unemployment declined to 4.7%, consumer confidence deteriorated sharply, with the GfK index falling to -24 from -13. The combination of persistent inflation and weakening household sentiment presents a difficult environment for the Bank of England, with markets increasingly anticipating a further interest rate increase in November.
Japanese equities experienced a difficult week, reflecting the broader global sell-off in technology shares and concerns around AI-related investment. Inflation also remained in focus, with core consumer prices rising 2.1% year on year in September, up from 1.7% in August and moving back above the Bank of Japan’s 2% target. While further monetary tightening remains possible, the central bank is expected to hold rates steady at its upcoming meeting.
Chinese markets also came under pressure, particularly in Hong Kong, where technology and internet-related shares led the declines. Economic data provided a more encouraging headline, with third-quarter GDP growth accelerating to 4.5% year on year from 4.3%, ahead of expectations. However, underlying activity remains uneven, with September retail sales increasing just 1.1% and fixed-asset investment declining 7.2% over the first nine months of the year. Weak domestic demand and investment continue to weigh on the broader recovery.
Geopolitical tensions remained another important driver of market sentiment. Renewed attacks on Saudi Arabian infrastructure by Houthi forces raised concerns about potential disruptions to energy supplies, pushing Brent crude oil above $116 per barrel. Higher energy prices continue to complicate the inflation outlook, reinforcing expectations that central banks may need to maintain restrictive monetary policy for longer.
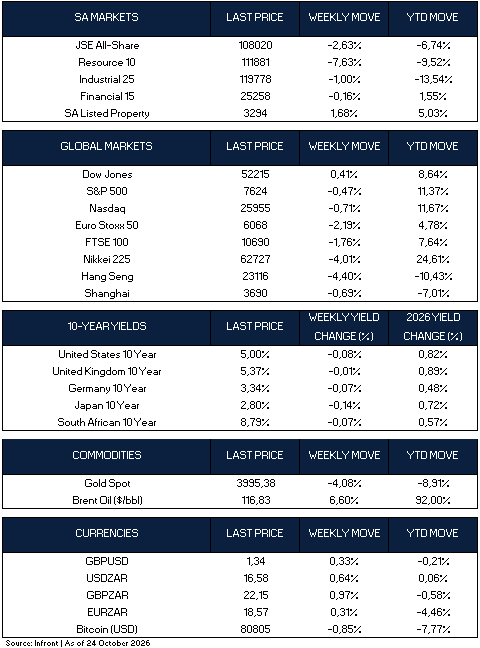
Overall, global equity markets ended the week weaker. The S&P 500 declined 0.47% and the Nasdaq fell 0.71%, while the Dow Jones gained 0.41%. European markets also retreated, with the Euro Stoxx 50 down 2.19% and the FTSE 100 losing 1.76%. Asian markets experienced sharper declines, led by Hong Kong’s Hang Seng, which fell 4.40%, and Japan’s Nikkei 225, down 4.01%. Brent crude oil gained 6.60%, extending its year-to-date increase to 92.00%. In contrast, gold declined 4.08%, its sharpest weekly fall since June, briefly slipping below $4,000 an ounce. Bitcoin also weakened, declining 0.85%.
Market Moves of the Week:
Turning to South Africa, the week was dominated by the government’s Medium-Term Budget Policy Statement. National Treasury lowered its 2026 economic growth forecast to 1.2% from 1.6%, highlighting the challenges facing the domestic economy. However, stronger tax collections have helped improve the government’s financial position, allowing it to reduce planned bond issuance and introduce a programme to repurchase some existing debt. These developments were welcomed by bond investors. Government also outlined additional infrastructure investment plans, although weak economic growth and elevated debt levels remain important challenges.
Inflation provided some encouraging news, despite rising slightly to 4.5% in September from 4.4% in August. The increase was smaller than expected, while underlying price pressures showed signs of easing. Importantly, government announced temporary fuel levy reductions from November to provide relief to households and businesses facing higher petrol and diesel prices. This should help cushion the impact of rising global oil prices and supports expectations that the South African Reserve Bank will leave interest rates unchanged at its November meeting.
Elsewhere, economic data continued to reflect a mixed picture. Retail sales increased 3.3% year on year in August, slightly below July’s 3.4% but ahead of expectations, suggesting consumer spending remains relatively resilient. However, business confidence softened and building activity weakened, highlighting the uneven nature of the economic recovery. While consumers continue to show some resilience, stronger business investment and confidence will be important to support a more sustained improvement in economic growth.
Against this backdrop, South African financial markets experienced a difficult week. The JSE All Share Index declined 2.63%, driven by a sharp 7.63% fall in resource shares, while industrials and financials retreated 1.00% and 0.16% respectively. Listed property was a relative bright spot, gaining 1.68%. The rand weakened against the US dollar to R16.58, while the South African 10-year government bond yield declined to 8.79%, supported by a more favourable government borrowing outlook following the budget announcement.
Chart of the Week:
Important Information
The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any STRATEGIQ Capital product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.
STRATEGIQ Capital is an authorised financial services provider (FSP 46624).