Global markets navigated another eventful week as investors balanced tighter monetary policy, elevated energy prices and mixed economic data. Central banks remained firmly in focus, with the Federal Reserve and the Bank of Japan raising rates, while the Bank of England remained on hold. Against this backdrop, equity markets were mixed, bond yields remained volatile and energy prices continued to influence the inflation outlook.
In the US, technology shares proved relatively resilient, helping the Nasdaq outperform, while smaller companies lagged. Sentiment towards AI-related stocks also improved as the week progressed, following an initially cautious reaction to renewed debate around the risks associated with advanced AI development.
The Federal Reserve raised the fed funds target range by 25 basis points to 3.75%–4.00%, its first increase in three years. With the move widely anticipated, attention shifted to the Fed’s updated projections, which showed a firmer inflation outlook and suggested that another increase remains possible before year-end. Stronger growth and employment assumptions also indicate that policymakers believe the economy can absorb somewhat tighter monetary conditions.
Economic data remained mixed but generally resilient. Retail sales rose strongly in August and initial jobless claims declined, while manufacturing surveys softened and housing activity remained under pressure. The US 10-year Treasury yield briefly moved above 5.0%, reflecting uncertainty around the future path of rates, while oil prices remained volatile amid renewed concerns over Middle East supply disruptions.
In Europe, inflation remained the central theme. Eurozone consumer inflation accelerated to 3.2% year on year in August, largely reflecting higher energy costs, while core inflation remained more contained at 2.4%. Industrial activity stayed weak and economic sentiment softened, with the ZEW expectations index declining in September, reinforcing concerns around the strength of the region’s recovery.
In the UK, the Bank of England kept its policy rate unchanged at 3.75%, although the 6–3 vote highlighted continued concern around inflation. UK inflation rose to 3.1% in August, while unemployment remained steady at 4.9%. With price pressures still above target but economic activity relatively subdued, policymakers continue to face a difficult balance between containing inflation and avoiding unnecessary weakness in growth.
Japanese equities ended the week higher, supported by a recovery in technology shares and a weaker yen, which provided a tailwind for exporters. The Bank of Japan raised its policy rate by 25 basis points to 1.25%, its highest level in more than three decades. While the move was expected, the split vote and limited guidance on the pace of future increases suggested that further tightening may proceed cautiously.
Chinese markets were more mixed, with mainland equities proving more resilient than Hong Kong. Technology shares recovered towards the end of the week, led by semiconductor and AI-related companies. Economic data continued to highlight an uneven recovery, with industrial production accelerating to 5.2% year on year in August, while retail sales growth remained subdued at just 0.4%. Weak investment, ongoing property-sector pressure and softer credit growth continue to weigh on domestic demand.
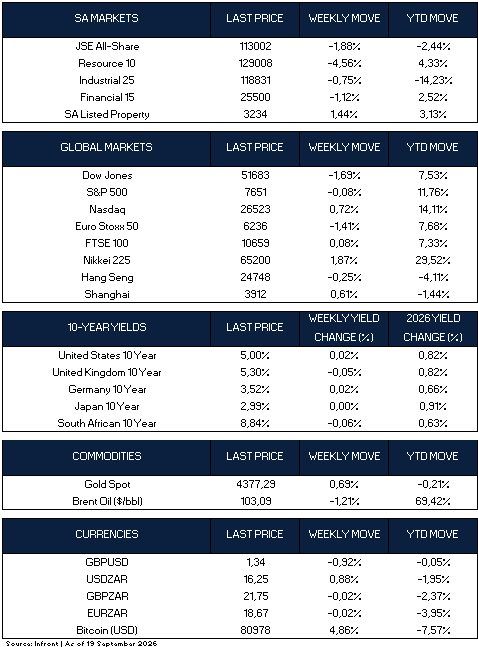
Overall, global markets delivered a mixed performance. The S&P 500 edged 0.08% lower, while the Nasdaq gained 0.72% and the Dow Jones declined 1.69%. The Euro Stoxx 50 fell 1.41%, while the FTSE 100 was broadly unchanged. Asian markets were stronger overall, led by Japan’s Nikkei 225, which gained 1.87%. Brent crude oil fell 1.21% for the week but remains 69.42% higher year to date, while gold gained 0.69% and Bitcoin rose 4.86%.
Market Moves of the Week:
Turning to South Africa, the latest data painted a mixed picture. Manufacturing conditions remained under pressure, with the Absa/BER Manufacturing Confidence Index declining to 27 from 31 and remaining below its long-term average. Around 70% of manufacturers continued to describe business conditions as unsatisfactory, with weak domestic sales and export orders weighing on sentiment.
The consumer backdrop was more encouraging. Real retail sales increased 3.4% year on year in July, ahead of expectations; and up from a revised 1.1% in June. Consumer confidence also improved, with the FNB/BER Consumer Confidence Index rising to -13 from -19. While households continue to face pressure from elevated fuel and borrowing costs, the data suggest that consumer spending is holding up better than activity in parts of the industrial economy.
Inflation expectations also remained relatively well contained. Expectations for 2026 were unchanged at 4.4%, while expectations for 2027 eased to 4.0%. Household inflation expectations declined more noticeably, an encouraging development for the South African Reserve Bank as it assesses the potential impact of higher oil prices and external cost pressures.
Against this backdrop, South African markets had a difficult week. The JSE All Share Index fell 1.88%, led by a 4.56% decline in resource shares, while industrials and financials declined 0.75% and 1.12% respectively. Listed property provided a relative bright spot, gaining 1.44%. The rand weakened against the US dollar, which closed the week at R16.25, while the South African 10-year government bond yield declined to 8.84%.
Chart of the Week:
Important Information
The information included above as well as individual companies and/or securities mentioned should not be construed as investment advice, a recommendation to buy or sell or an indication of trading intent on behalf of any STRATEGIQ Capital product. This material is provided for informational purposes only and is not intended to be investment advice or a recommendation to take any particular investment action. Information contained herein is based upon sources we consider to be reliable; we do not, however, guarantee its accuracy. All charts and tables are shown for illustrative purposes only.
STRATEGIQ Capital is an authorised financial services provider (FSP 46624).